
👋 Hey, Nick here. A big welcome to the new subscribers from Hartford Investment Management Company, Armada Credit, and Crestwood Advisors. You’re now one of the 3,558 subscribers, and you’re reading the 189th edition of my private credit newsletter.
Reading on Outlook? The charts won’t render. Read it online
📕 Reads of the Week
We hedge because the future is uncertain, because highly leveraged capital structures have finite capacity for surprises, and because adapting to a new environment takes time.“
Market Updates
Apollo: The Strategic Case for Allocating to Asset-Backed Finance
PitchBook: US Private Credit Monitor
YTD volume runs 16% behind last year’s pace, while deal count trails by 10%
The BSL–direct lending spread gap has widened to 166 bps over the past three months, up 43 bps from Q1 2026.
Direct lending accounts for nearly half of US private debt capital raised over the trailing 12 months.
PitchBook: European Private Credit Monitor
Direct Lending is down 16% compared to 2025, although Q3 was the highest quarterly volume so far in 2026. The year-over-year level.
YTD in Europe, all direct lending LBOs have priced with new issue spreads under 600 bps
None of the 10 largest direct lending deals were done in 2026
Moody’s: the real default rate is 5.8%, not 4%
About 17% of these borrowers pay some interest in kind (PIK).
Business services, consumer services and software account for half of all defaults.
Maturities peak in 2028. Borrowers rated Caa (deep junk) or account for over half of the 2027–28 maturities.
Manager Updates
WhiteHorse Capital is pursuing a credit secondaries transaction involving its publicly traded BDC. The transaction would transfer all assets from the BDC, WhiteHorse Finance into a closed-end continuation vehicle backed by private credit secondaries investors. Link
Blue Owl is planning a ‘big push’ into insurance. “We are not managing enough capital…. We’re realising that if we had a bigger pool of capital, meaning insurance capital, we could provide really unique solutions . . . It’s something we’re going to make a big push in.” Link
Victory Park Capital has partnered with Tradable to launch VALTS, a tokenized feeder fund providing qualified US investors access to its private asset-backed credit interval fund via the Stellar blockchain. The fund will offer monthly income distributions in stablecoins, expected quarterly liquidity, and the ability to transfer tokens between pre-approved investors. Link
Partnership Updates
Orion Infrastructure Capital partnered with Liberty Mutual Investments to launch a new Credit Income Strategy focused on middle market infrastructure debt opportunities. The partnership gives LMI the option to deploy up to $750 million of capital with OIC’s infrastructure platform. Link
Benefit Street Partners partnered with Encina Lender Finance to expand its ABF platform. BSP acquired an initial $480 million portfolio originated by Encina. In addition, a 14-person investment team from Encina joined BSP and will continue to manage and originate investments through the strategy. Link
Goldman Sachs partnered with Phoenix Financial, an Israeli asset manager, to deploy more than $4bn (£3bn) across global private credit opportunities. The deal will see the firms collaborate on investments across corporate credit, asset-backed finance, real estate and infrastructure debt. Link
“Don't congratulate us when we buy a company. Any fool can buy a company; you just need to pay enough.
The hard part is what you do with the business once you own it. Congratulate us when we sell it, after we have created real value.”
📈 Charts of the Week
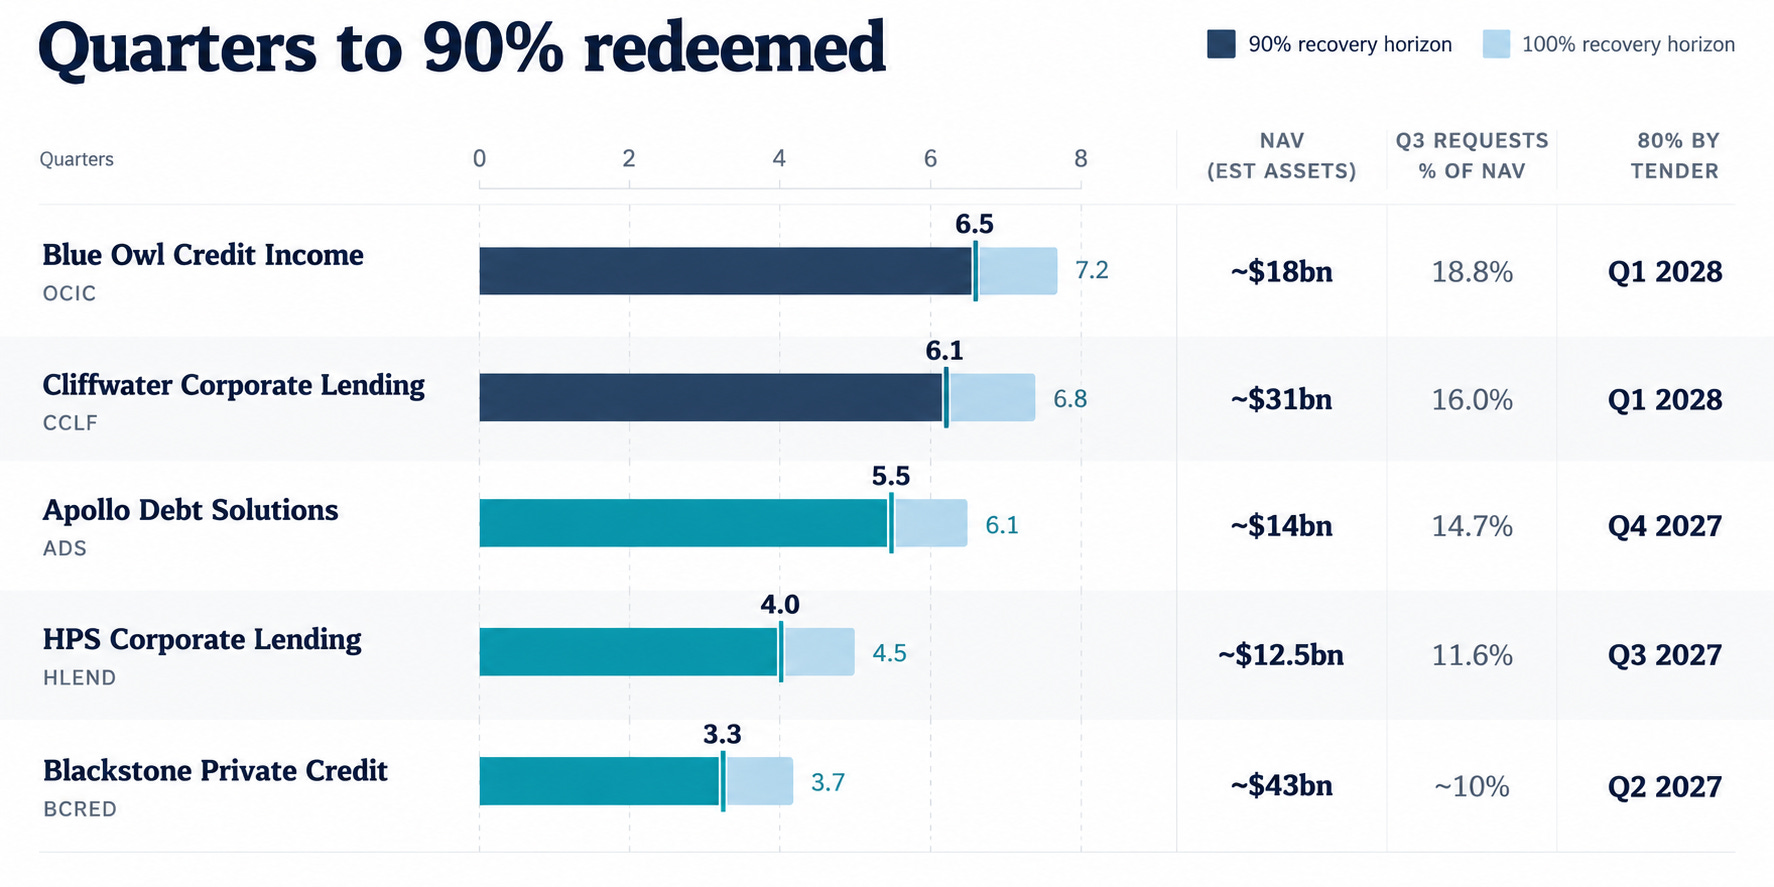
How Long Does it Take to Exit Non-Traded Private Credit Funds?
A redemption queue doesn't mean capital is lost. Here's how long investors may have to wait to get it back.
Why 90%?
When redemption requests exceed a fund’s quarterly 5% limit, investors receive a pro-rata share of their outstanding requests. The remainder rolls into the next quarter, assuming investors re-tender.
At OCIC’s approximately 30% fill rate, an investor receives 30% of the original request in the first tender, 21% in the second and 15% in the third. Each subsequent payment gets smaller.
We use 90% as a practical measure of a near-complete exit. The model assumes Q3 2026 fill rates remain constant, although in practice investors could exit sooner if redemption demand falls below the fund’s repurchase limit. Future demand could also rise, extending the wait.
Calculation: Cumulative redemption after n tenders = 1 − (1 − f)n, where f is the quarterly pro-rata fill rate.
Ares: Private Credit Outperformance Depends on How You Measure It
Benchmark choice and measurement method can materially affect conclusions about private credit performance.
Widely circulated recent research compared drawdown-fund multiples with buy-and-hold ETF returns.
Measuring in this way ignores the timing of capital calls, distributions, and residual value.
Ares cash flow based benchmarking found that private credit performance diverges meaningfully from the Hooke et al. (2025) results when using the same benchmarks but accounting correctly for cash flow timing.1
The median vintage IRR was 7.6%.
This shows a vintage Direct Alpha of 3.3% per year vs. a public loan comparable.
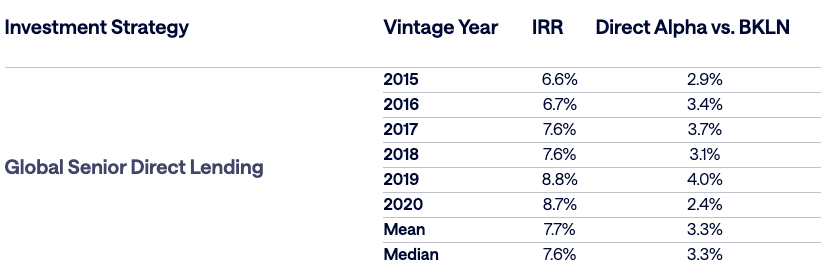
BlackRock Quarterly: Private Credit Returns are Falling
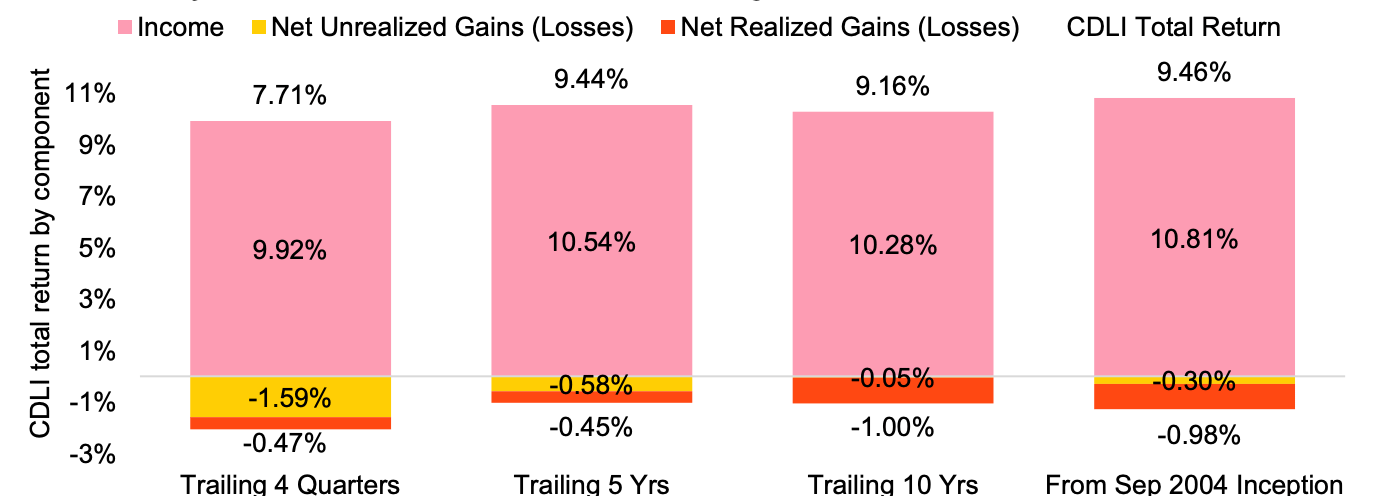
Tighter spreads and higher unrealized losses have been a considerable headwind
BlackRock expects unrealized losses to come down. A Cliffwater analysis of prior stress periods found that subsequent realized losses equaled roughly half of preceding unrealized losses, as some markdowns ultimately reverse.
💰Fundraising News
M&G’s UK LTAF
M&G, a UK-based investment manager, launched its first LTAF, with initial commitments of ~$100 million. The fund allows UK defined contribution pension schemes to invest in private credit and aligns with the ambitions of the Mansion House Accord.
This newsletter is for educational and entertainment purposes only. It should not be taken as investment advice.