
👋 Hey, Nick here. A big welcome to the new subscribers from Sumitomo Mitsui DS Asset Management, Dukas Lindein PR, and MUFG. You’re now one of the 3,542 subscribers, and you’re reading the 188th edition of my private credit newsletter.
Reading on Outlook? The charts won’t render. Read it online
📕 Reads of the Week
“As big as data center development and buildout is, climate transition is much bigger.”
Calpers Plans to Step Up Private-Credit Allocations to Climate Solutions
Market Updates
KKR: Q3 2026 Market Review
California has a history of rewarding those willing to look beneath the surface. Gold in the rivers and oil beneath the ground. Each resource triggered a rush of capital, but the enduring value was rarely created by the natural resource alone. Much of it accrued to those who supplied the tools, financed the claims, and built the roads, railways, and pipelines that turned discovery into an economy.
Investment in that infrastructure transformed what lay beneath the ground into an asset, a stream of cash flows, and ultimately something a balance sheet could capture.
Brookfield: Credit Quarterly:
Four years after the sea change in interest rates began, the tide hasn’t reversed. The rate hikes of 2022 weren’t just a blip in a multidecade yield compression trend—they initiated a fundamental repricing of capital.
Expected rate cuts have not materialized and government bond yields are well above 2022 levels, with the U.S. 10-year Treasury yield recently crossing the symbolic 5% threshold.
Elevated rates therefore continue to shape the market environment, creating a richer opportunity set for credit investors but also a heavier burden for borrowers. The latter is manifesting in clear dispersion in the fates of weaker and stronger borrowers.
It appears this is the ‘‘new normal’’ for interest rates, but what does it mean for credit investors?
Manager Updates
🎧🎧Recommended Listen: Former Google CEO Eric Schmidt speaks to Blackstone about AI. Link
Apollo extends Daily Pricing across various direct lending, asset-backed finance, multi-credit and opportunistic credit vehicles. So far The trading desk has handled around 500 assets with 160 counterparties. Link
BC Partners Credit commits up to $300m to fund LIV Golf restructuring
Partnership Updates
SMBC and Ardian, a Paris-based private markets firm, partnered to launch a NAV financing platform. The partnership brings together two complementary strengths in NAV financing. SMBC has a long-standing track record in the large-cap segment, with deep structuring expertise and a strong global franchise. Ardian, through its Secondaries & Primaries expertise, brings mid-cap insights, local market access, and proprietary data on private market assets. Link
StepStone partnered with ASB Capital, a Dubai-based wealth manager, to launch a Shari’ah-compliant private credit vehicle. The open-ended fund will invest in US middle-market loans and is aimed at institutional and sophisticated investors globally. Link
📈Charts of the Week
What does it take to 10x your money?
Many financial advisors talk to their clients about how to double their money, but Ares believes few speak in terms of growing wealth by 10x, perhaps because it seems unattainable.
Ares belives the rate and consistency of annual returns that private market funds, particularly private equity, seek and obtain may help make that 10x mindset a reality.
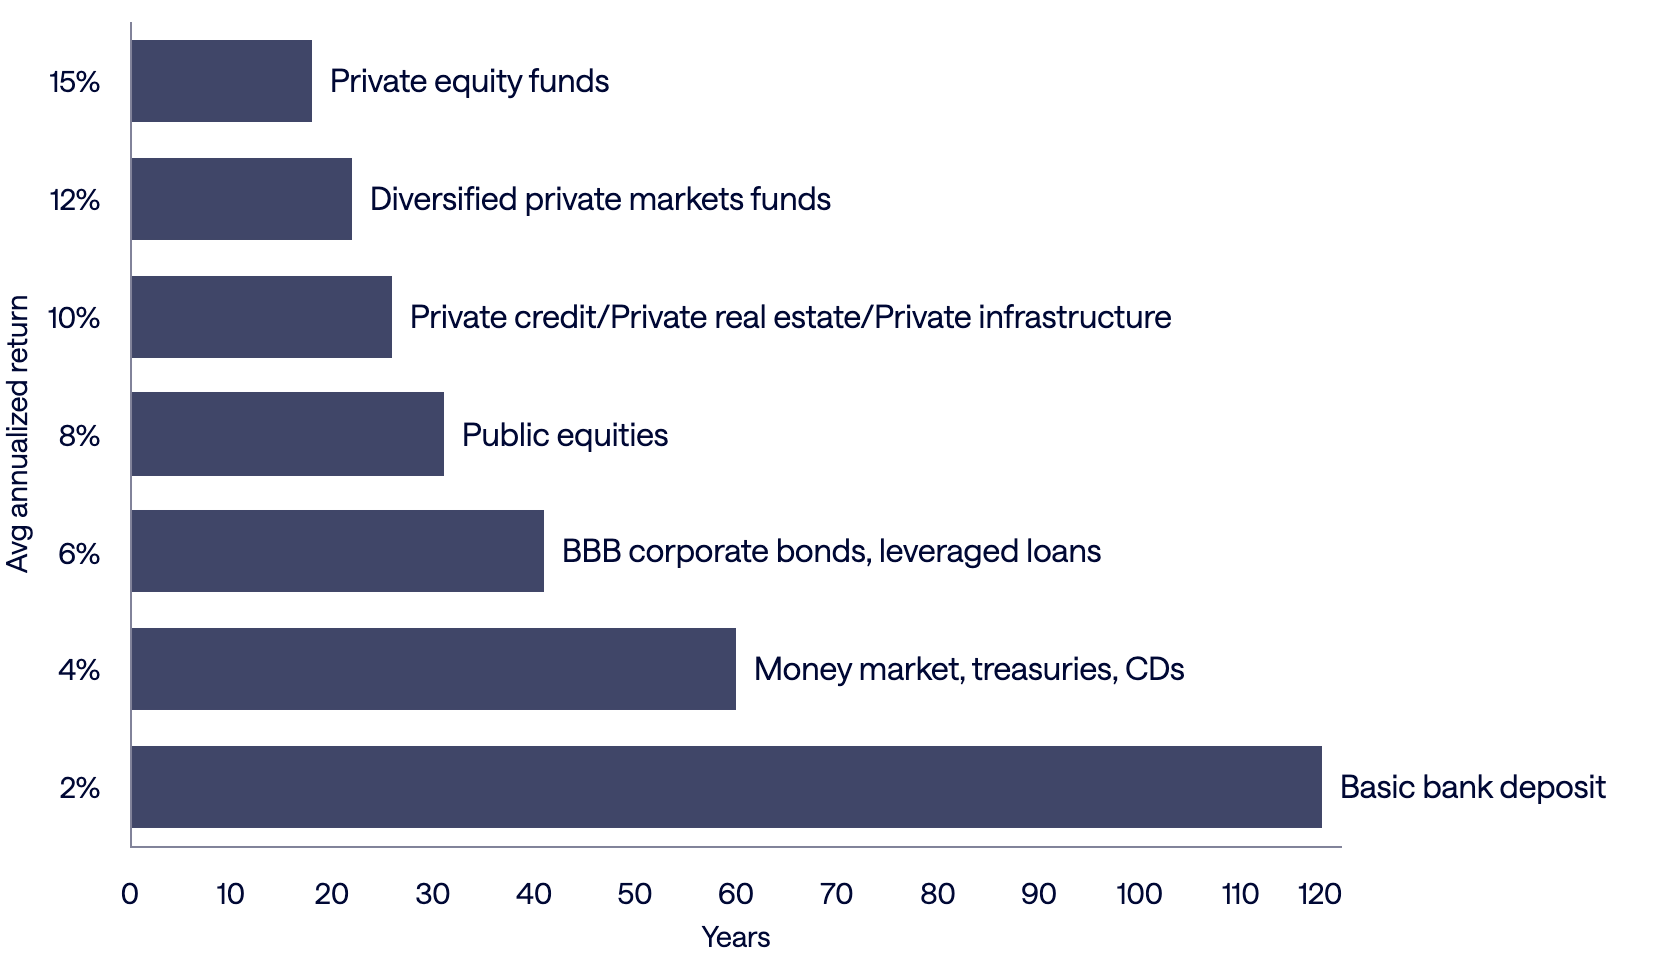
👉 Ares: What does it take to 10x your money?
Things could get messy in software
Recent difficulties refinancing software deals in syndicated markets hint at discomfort ahead, particularly for those SaaS platforms originally underwritten with aggressive (i.e., >15x recurring revenue) enterprise value assumptions
Ytd Reduction in 2028 Maturity Wall
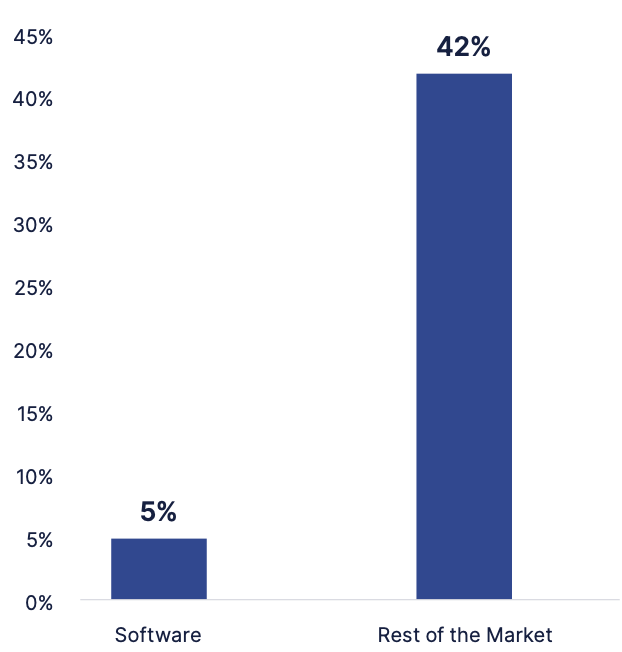
👉 Carlyle Financing AI without a SaaS repeat
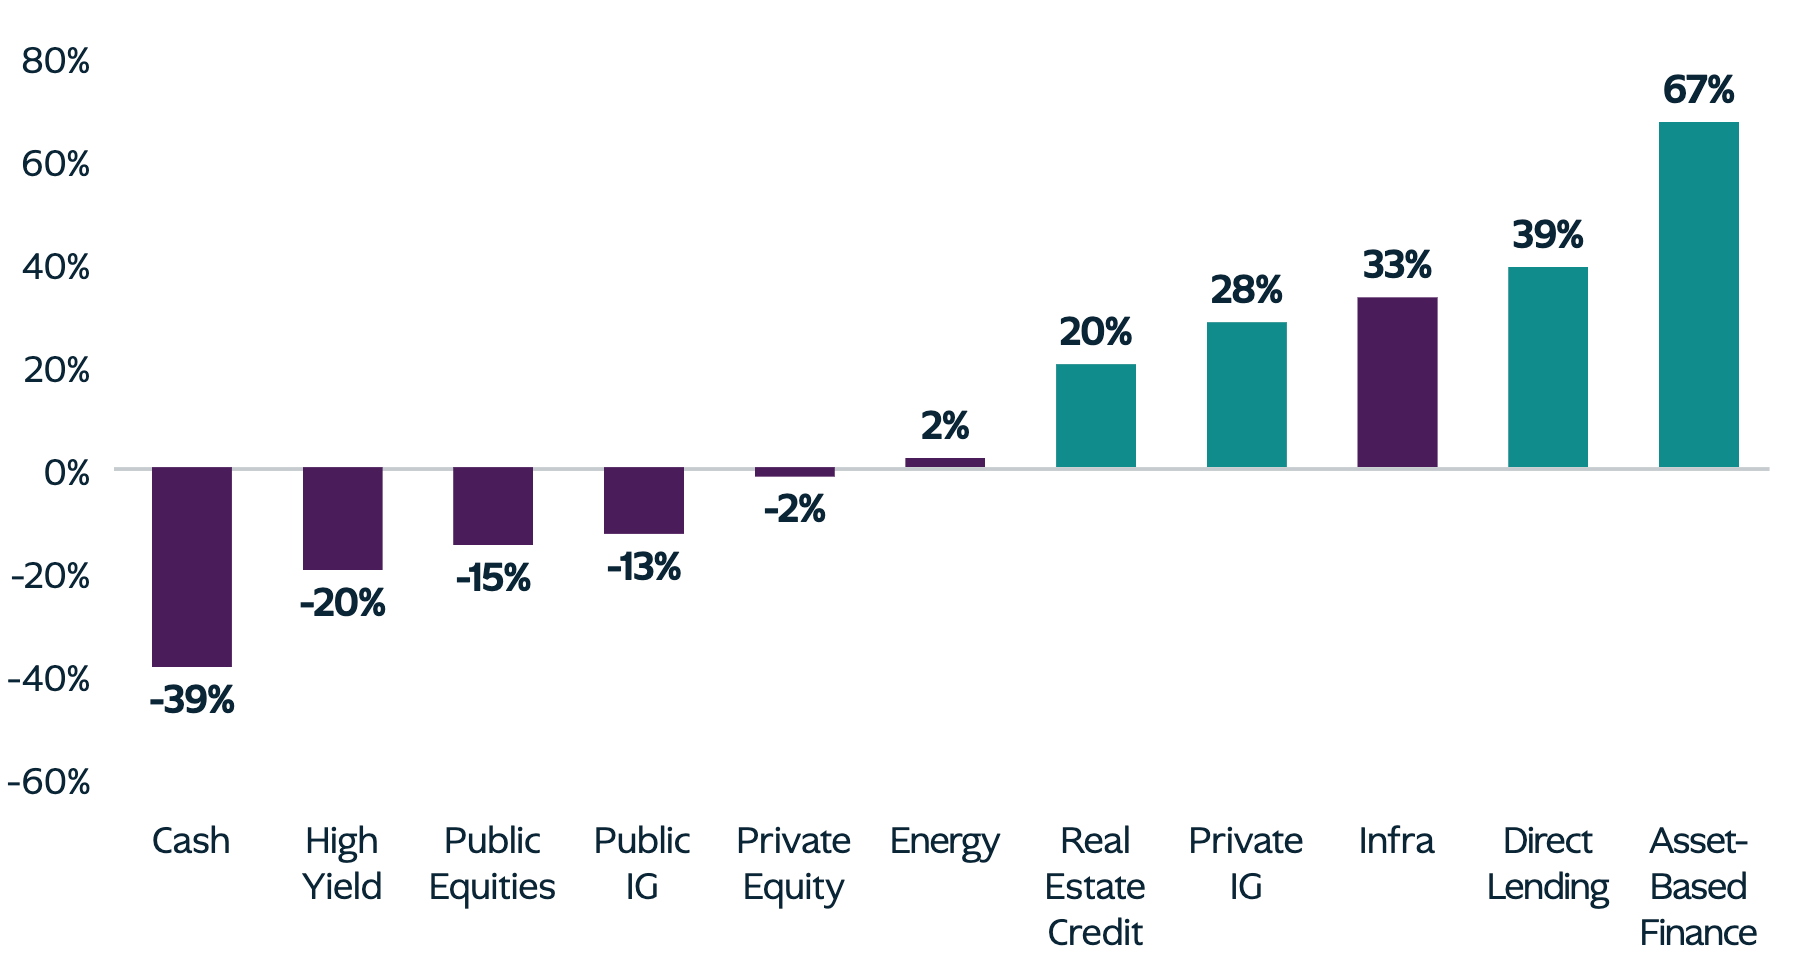
Where Insurers Plan to Add vs. Reduce Risk Over 12–24 Months
KKR surveyed 50 U.S. insurers representing nearly $2.6 trillion in assets under management.
Insurers plan to increase their exposure across every private credit category
💰Fundraising News
Audax Private Debt $10bn Direct Lending Fund III
Audax Private Debt, a New York-based manager, closed its $10 billion Direct Lending Fund III. The fund will lend to sponsored North American companies, typically with $15 million to $75 million of EBITDA.
Centerbridge’s $4 billion Special Credit Partners V
Centerbridge Partners, a New York-based investment manager, raised $4 billion for its Special Credit Partners V.
Oaktree $2bn ABF Fund
Oaktree closed its debut Asset-Backed Finance Fund with $2 billion of commitments. Oaktree’s ABF strategy focuses on providing capital to originators across a range of sectors including equipment leasing, transportation, consumer, real estate and infrastructure.
Blackstone $1 billion Continuation Fund
Blackstone raised a $1 billion continuation vehicle for its Capital Opportunities Fund IV, which completed fundraising in 2022. Allianz Global Investors and StepStone reportedly lead the transaction. The original fund has a reported net IRR of 11%.
Nuveen $660m Australian CRE Debt First Close
Nuveen, a New York-based asset manager, announced a first close of more than $660 million for its Australian commercial real estate debt strategy. The core-plus strategy provides structured senior and junior loans with modest leverage and financial covenants, with a preference for urban industrial and logistics and residential assets.
Fidelity Investments $451m Real Estate Opportunity First Close
Fidelity Investments, a Boston-based asset manager, closed its $451 million Real Estate Debt Opportunities Fund II. The fund invests primarily in US private commercial real estate loans across property sectors, with flexibility to buy tradeable real estate debt. Its mandate includes middle-market subordinated and mezzanine loans, originated financing, and secondary loan purchases.
BlueOrchard $300m Emerging Markets First Close
BlueOrchard, a Switzerland-based impact manager, announced a first close of $300 million for its launched emerging-markets private debt vehicle. The evergreen strategy is managed by BlueOrchard, part of Schroders, and is designed to channel institutional private debt capital into emerging-market companies.
Corre Partners $220m First Close
Corre Partners, a US-based opportunistic credit manager, announced the first close of Horizon III with $220 million raised. The fund has a $500 million target and a $650 million hard cap. It invests in opportunistic credit in middle-market companies facing temporary financial pressure or undergoing a turnaround. Its predecessor, Horizon II, reported a net IRR of 24.7 percent and a net MOIC of 2.4x as of 30 June 2026.
HMG European Private Real Estate Debt Fund VI
HanseMerkur Grundvermögen, a Hamburg-based real estate manager, launched its sixth real estate debt fund, Private Real Estate Debt Fund VI, with a target of ~$560m million. The fund will provide whole-loan financing to commercial and residential property developers across Europe.
Partners Group Global Multi-Sector Private Credit Income
Partners Group launched a new Global Multi-Sector Private Credit Income Strategy through an open-ended evergreen vehicle for institutional and private wealth investors. The strategy combines senior direct lending, credit secondaries, fund financing, royalties, opportunistic credit and liquid credit across Europe, North America and Asia-Pacific, targeting high-single-digit to low-double-digit returns.
Ares Management raised approximately $4.2 billion for its inaugural Ares Global Structured Solutions Fund and affiliated vehicles, more than four times its original $1 billion target. The strategy sits within Ares’ secondaries business and provides preferred equity and bespoke capital to private-market managers, including financing GP fund commitments, seeding new strategies through structured LP commitments and supporting succession transactions. It is not conventional corporate direct lending, but it fits your capital-solutions / GP-financing universe. Ares Management
👉
This newsletter is for educational and entertainment purposes only. It should not be taken as investment advice.