
👋 Hey, Nick here. A big welcome to the new subscribers from Partners Group, Oaktree and Guggenheim Investments. You’re now one of the 3,414 subscribers, and you’re reading the 185th edition of my private credit newsletter.
Reading on Outlook? The charts won’t render. Read it online
📕 Reads of the Week
Market Updates
Lower mid-market stress has climbed more than tenfold since 2023. Loans below 90% of par for borrowers with EBITDA below $20 million have risen from ~1% in 2023 to 12% today. Houlihan Lokey
Private Credit Defaults Are 1%, 6% or 19%, Depending Who You Ask. Link
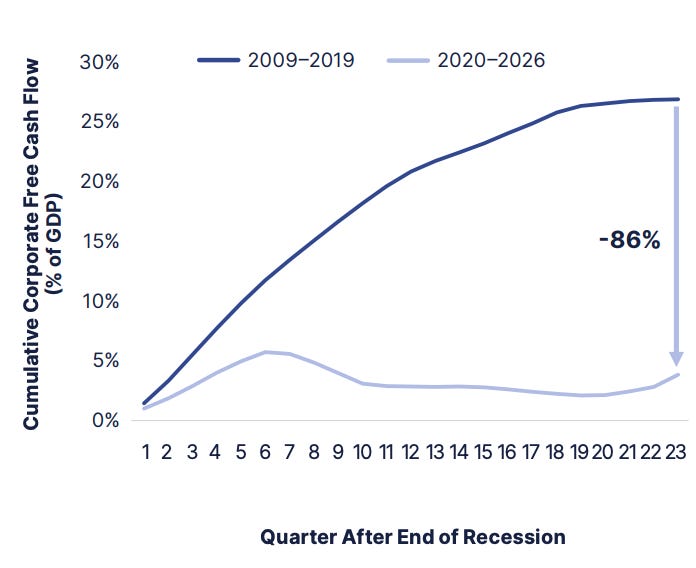
US corporate savings are down 86% vs. the last cycle
Much of that shift is attributable to the (formerly “asset light”) hyperscalers, which transitioned from the economy’s largest providers of liquidity to its largest users of it.
Manager & Deal Updates
KKR’s private investment-grade volume has reached $80bn so far this year, twice what it did in all of 2025. Link
A deep dive into Blackstone’s hybrid debt deal with Air Canada’s loyalty scheme. Link
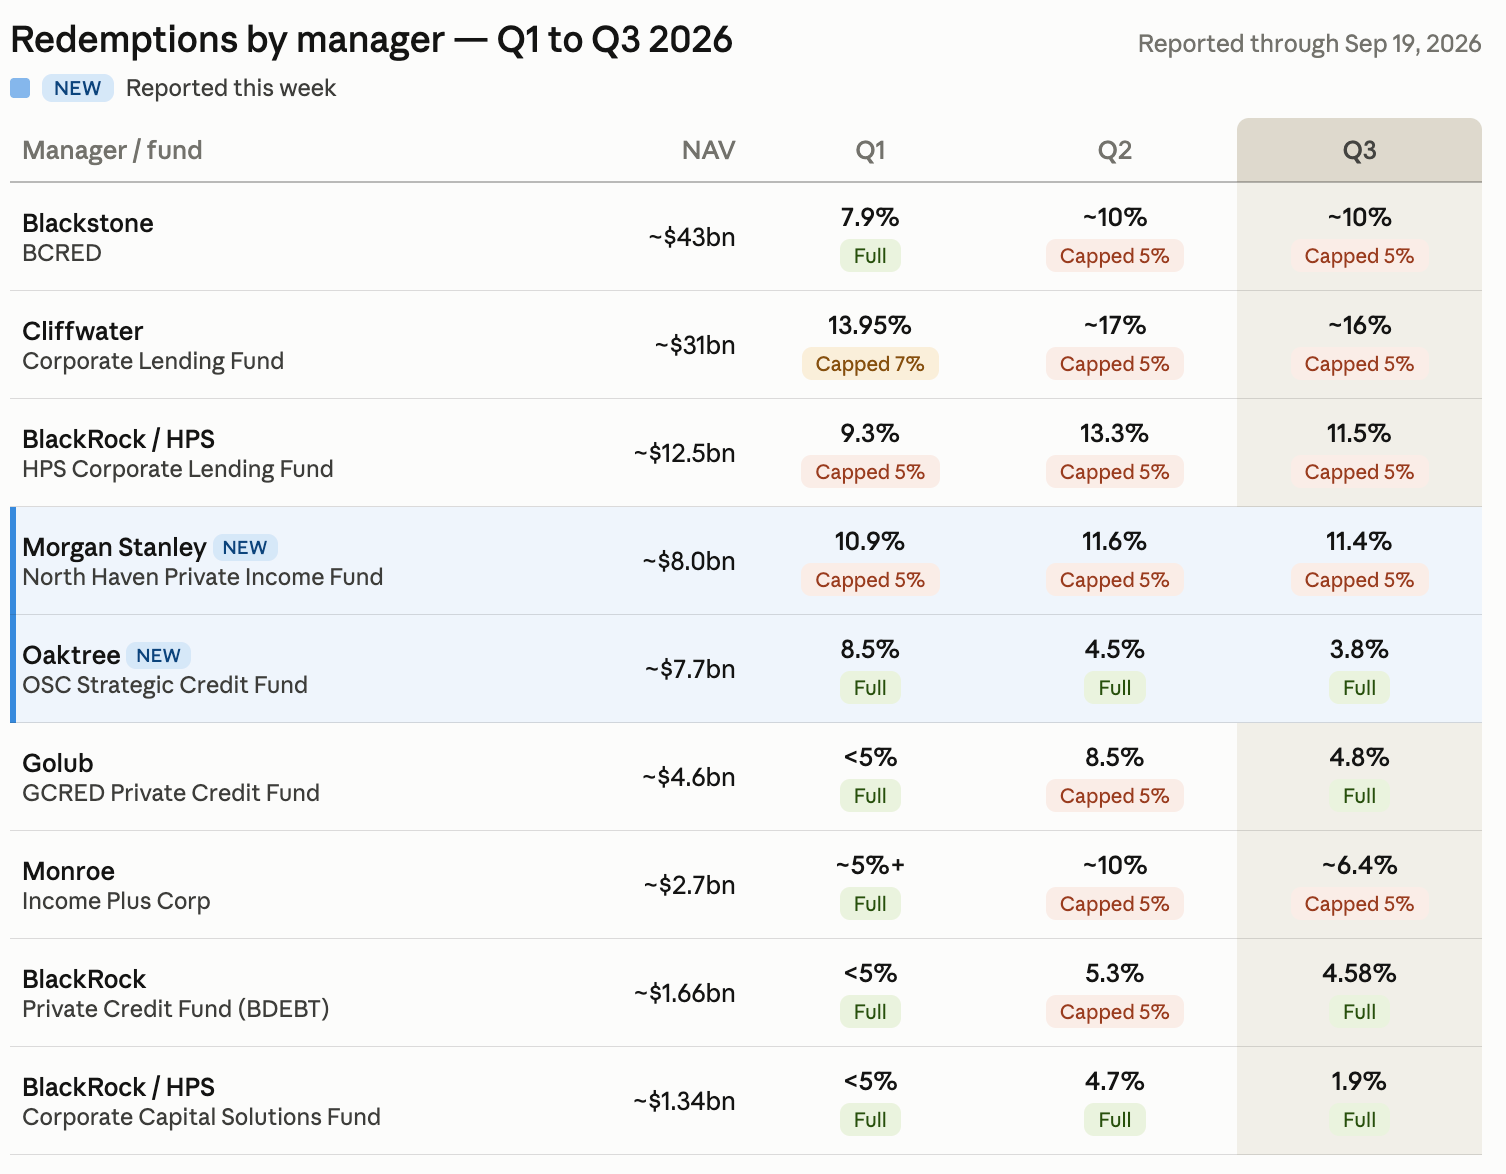
BDC Redemptions Q3 26 Update: Week 3
Last week saw two more BDC funds announce Q3 redemptions:
Redemption requests have fallen for all managers so far.
Oaktree’s Strategic Credit Fund received redemption requests lower than its cap
Morgan Stanley capped its redemptions at 5%.
Private Capital Fundraising Is Heading for a Fifth Straight Annual Decline
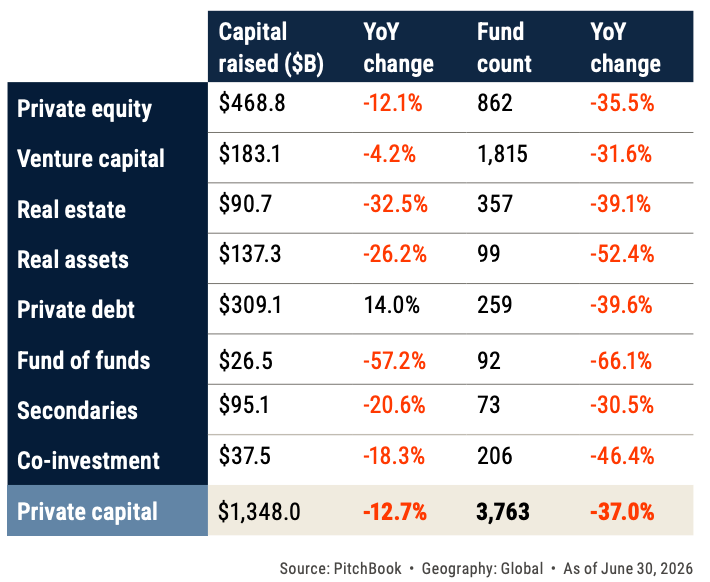
PitchBook published an update on global private market fundraising.
Below are my highlights:
👉 Read PitchBook’s Global Private Market Fundraising Report
Private markets have nearly tripled since 2016
AUM has risen from $6.1 trillion to $16.7 trillion.
However, this growth was driven in part by a period of exuberance for risk assets, with private capital fundraising peaking in 2021.
Since then, fundraising has been in a multiyear decline.
If the pace holds through year-end, the global fundraising total will decline for a fifth straight year.
YoY changes in trailing 12-month fundraising activity by strategy
Negative net cash flows since 2022 have tested investors’ resolve
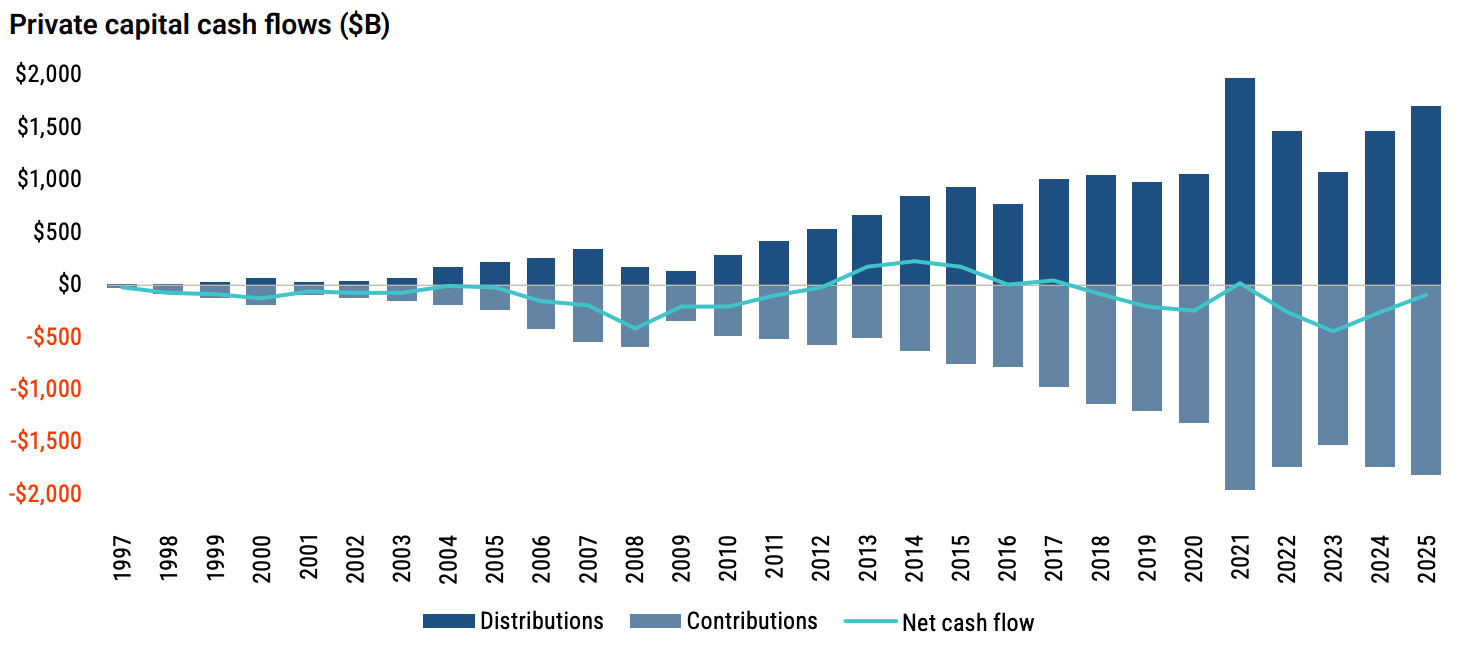
The cause of the fundraising slowdown is multifaceted.
Mature private markets mean that institutional investors’ allocations are bumping up against risk limits, and disappointing distributions are hindering the flywheel that replenishes new vehicles.
2023’s negative balance of $428.6 billion was the largest cash flow gap in records dating back to 1997.
Concentration is a prevailing theme
Funds larger than $1 billion continue to capture a greater share of total fundraising, reaching 78.2% in H1 2026, up from 59.1% in 2021.
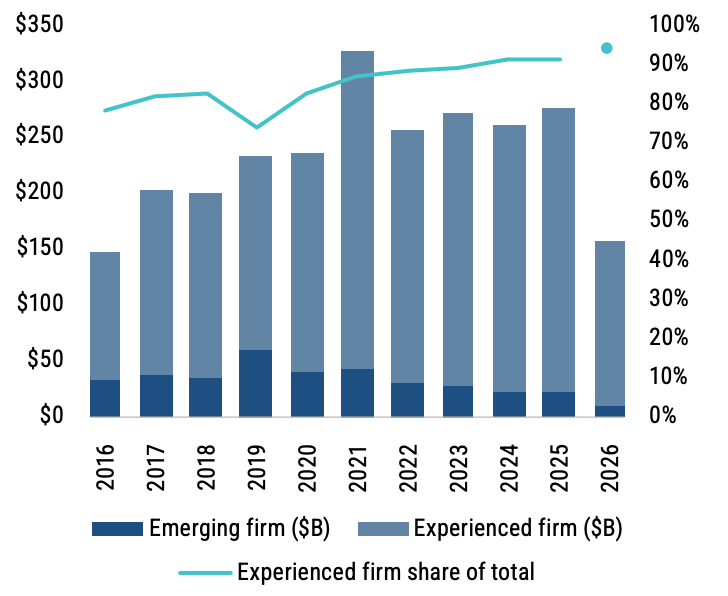
LPs are gravitating toward GPs with established track records
Aging NAV is a major concern for LPs
Sluggish distributions have resulted in almost $5 trillion of capital parked in funds that are 7 years or older.
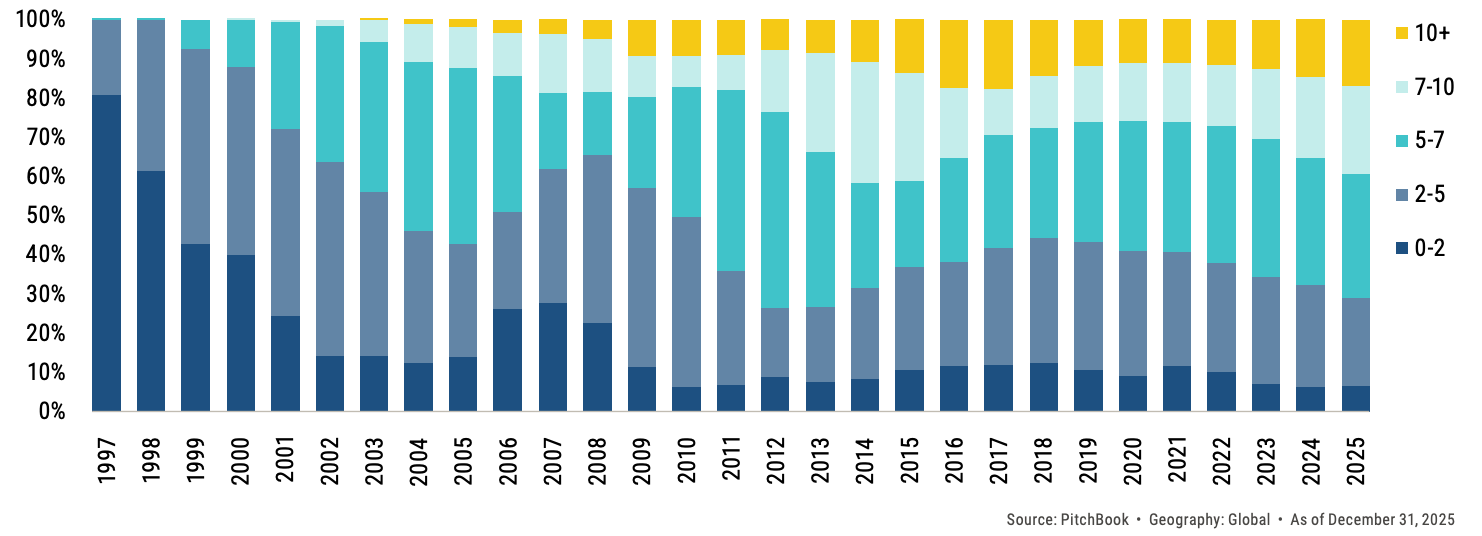
Private debt fundraising has fully entered its era of manager concentration.
Private credit managers closed on 88 funds totalling $158.3 billion in commitments in H1 2026.
PitchBook forecasts fewer than 200 closes by year-end, which would mark a fourth consecutive year of decline.
👉 Read PitchBook’s Global Private Market Fundraising Report
💰Fundraising News
Blackstone’s $8bn energy transition and digital infrastructure credit strategy
Blackstone is targeting at least $8 billion for the fourth vintage of its energy transition and digital infrastructure credit strategy. The fund will provide loans to businesses operating across energy security, power and utilities, data centres and semiconductor financing. The previous fund in the series raised $7.1 billion in 2023 and had generated a 15 percent net internal rate of return as of 30 June.
👉 PE Wire
Carlyle $2.3 billion Infrastructure Credit Fund II
Carlyle announced the final close of $2.3 billion for its Infrastructure Credit Fund II. The fund finances below-investment grade infrastructure businesses and assets across energy transition, digital infrastructure, transportation and logistics, low-carbon power, water and waste treatment, and other essential infrastructure sectors. It is more than three times larger than its predecessor.
Hines and Rialto $1.1bn US commercial office lending
Hines and Rialto Capital, a Houston-based real estate investment manager and a Miami-based credit specialist, announced the final close of Hines Rialto Credit Partners at $1.1 billion. The fund invests in US commercial office properties.
Stockdale’s $300 million Real Estate Credit
Stockdale Capital Partners, a Los Angeles-based real estate investment firm, launched a real estate credit platform and aims to write $300 million of loans over the next 12 months. The platform will provide senior bridge loans, mezzanine loans, note purchases and special situations investments across US commercial real estate, initially targeting loans of $15 million to $75 million.
BlueOrchard $250 million Climate Action Mobilisation
BlueOrchard, a Swiss impact investment manager, announced a first close of $250 million for its Climate Action Mobilisation Fund. The blended finance vehicle provides senior loans to banks, microfinance providers and other financial institutions that channel climate finance to small and medium-sized businesses across emerging and frontier markets.
Neuberger Specialty Finance Aviation Finance
Neuberger Specialty Finance, the New York-based specialty finance arm of Neuberger Berman, launched New Bridge AeroFinance. The aviation financing platform will target a portfolio of more than $2 billion.
👉 Neuberger Specialty Finance Announcement
This newsletter is for educational and entertainment purposes only. It should not be taken as investment advice.