
👋 Hey, Nick here. A big welcome to the new subscribers from Trinity Capital, Prefcap, and Calu Media. You’re now one of the 3,624 subscribers, and you’re reading the 191st edition of my private credit newsletter.
Sometimes I read a report, and it’s all I can think about. My wife knows this too well. She’ll ask me a question, and when I don’t reply, she just stops talking and waits. A minute later I catch up, apologise, and try to explain why I’m so excited about management fees. She hears me out like someone who cares deeply about management fees.
She doesn’t.
This week’s StepStone fee report is one of those. If you’re short on time, scroll straight to the main section.
Reading on Outlook? The charts won’t render. Read it online
📕 Reads of the Week
Market Updates
Carlyle | Global Private Markets Quarterly (Recommended read)
An 8% preferred return compounding over five years reaches 1.47x. Buyout firms currently mark their 2021 investments at a median 1.45x cost, just below that hurdle.
With higher valuations off the table, Carlyle believes some managers are shifting their focus from maximising carry on individual deals to ensuring the fund clears its hurdle.
US exit value rose 50% in Q3 to an estimated $166bn across 405 deals, potentially reflecting that shift.
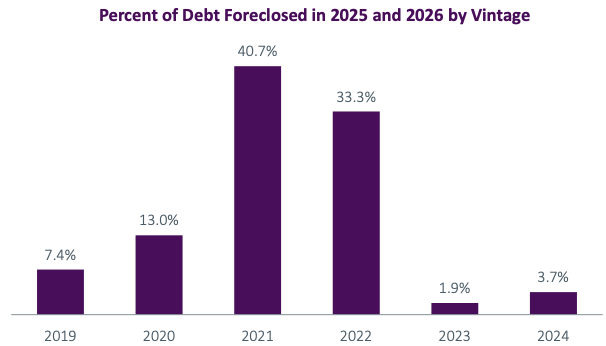
2021 and 2022 vintages reflect weaker underwriting
KKR | Global Wealth Playbook: Read the report
Manager Updates
AI compute financing
Anthropic | $63bn chip facility. Bank of America, Citi and Morgan Stanley are arranging the senior debt, and Blackstone is providing the second lien, to fund Anthropic’s purchase of Broadcom AI chips. Broadcom is supporting the chips’ residual value to protect senior lenders. Blackstone announcement
SpaceX | $40bn equipment lease. Apollo and Goldman Sachs are financing Nvidia AI chips. SpaceX will lease the chips from a financing vehicle and use the compute to power Grok and its cloud services. SpaceX announcement
Platforms & milestones
Apollo | European Credit Company. Apollo launched a new platform dedicated to European performing credit. It launches with more than €10bn of lending capacity and will act as a long-term financing partner across the region. Apollo announcement
Nuveen | $100bn milestone. Nuveen’s private credit platform, Churchill and Arcmont, has passed $100bn in committed capital. Churchill announcement
Partnership Updates
Apollo | Mubadala Capital $5bn Partnership. Apollo made a strategic equity investment in Mubadala Capital and is expected to commit $5bn to Mubadala Capital’s investment strategies. Apollo announcement
Man Group | Meiji Yasuda | $1.25bn Partnership. Meiji Yasuda Life Insurance intends to increase its commitments to Man Group strategies to $1.25bn over the next three years, with a particular focus on private credit. The two firms will also develop investment products for Japan. Separately, Meiji Yasuda is considering buying a stake of around 5% in Man Group through open-market purchases. Man Group announcement
Most of the supply is being contracted by the biggest, most well-capitalized companies in the world…
The scarce thing today, which you’re always looking for in economics, is the AI infrastructure. It’s not keeping up with the demand, which is growing so rapidly.
📈 StepStone: the state of direct lending fees
StepStone benchmarked the GP fees of 250 direct lending funds across the US and Europe. If you’re an LP, most of this is good news. If you’re a GP, there’s one consolation. I've redrawn StepStone's charts to make the trends easier to read.
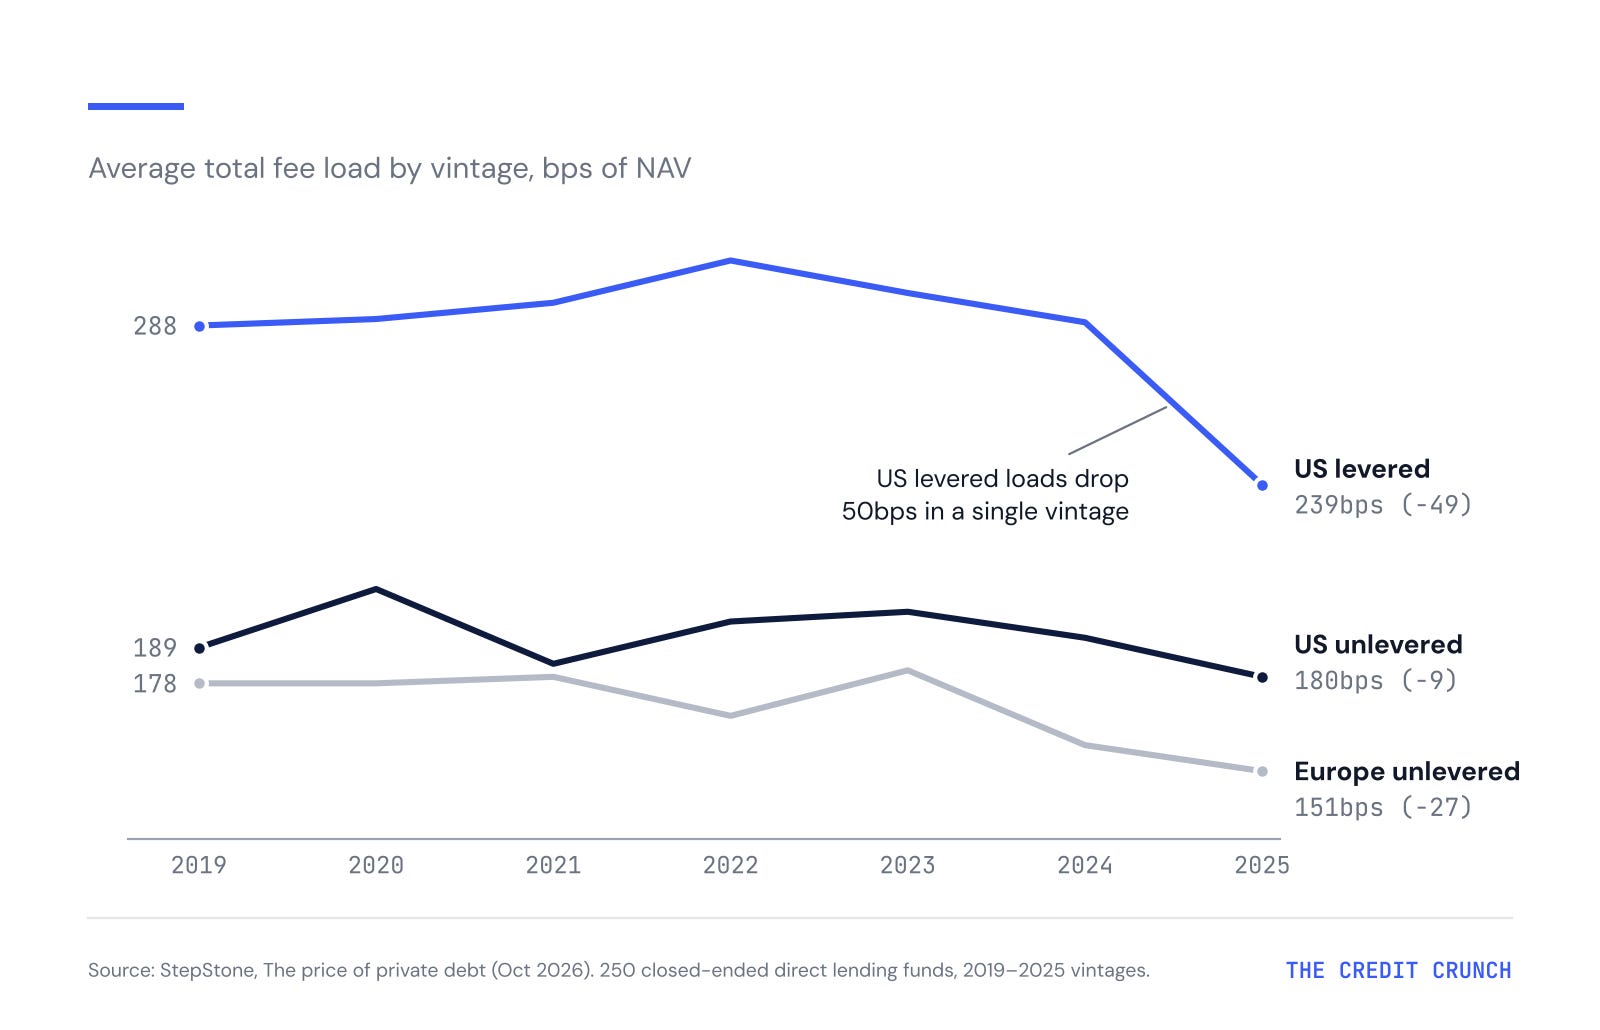
Fee Loads: Down across the board
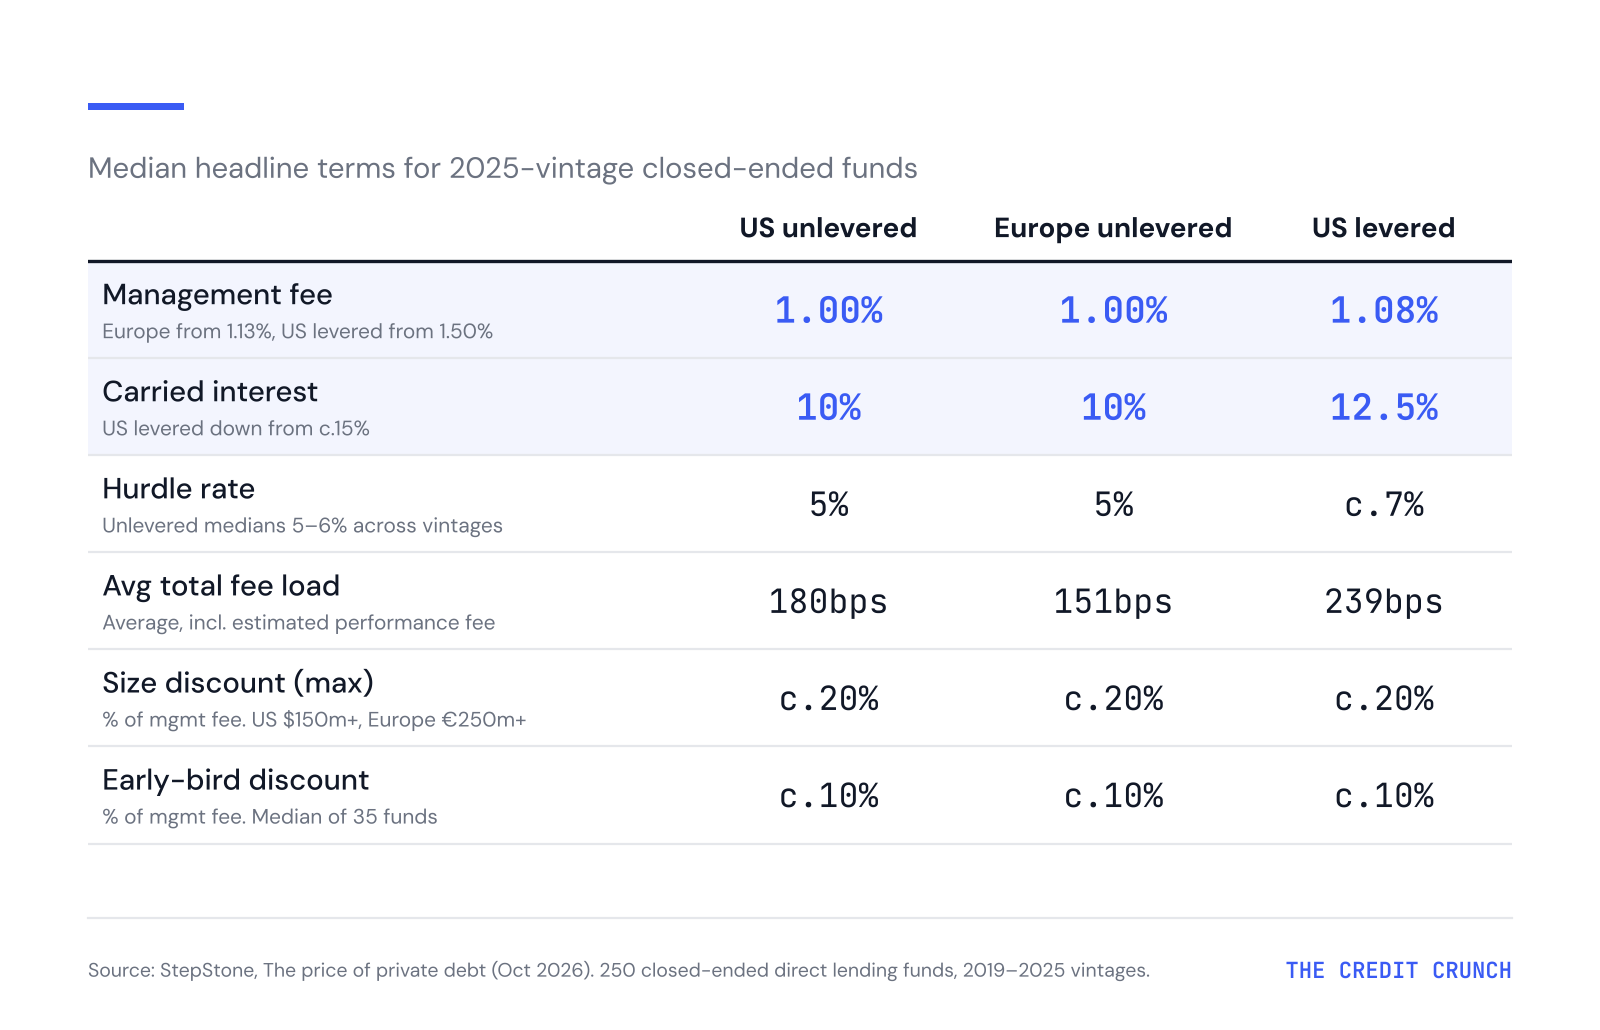
The average total fee load, management fee plus performance fee, fell in across the board between 2019 and 2025. US levered funds fell most, from 288bps to 239bps, though almost all of that came in the 2025 vintage. Europe remains the cheapest at 151bps.
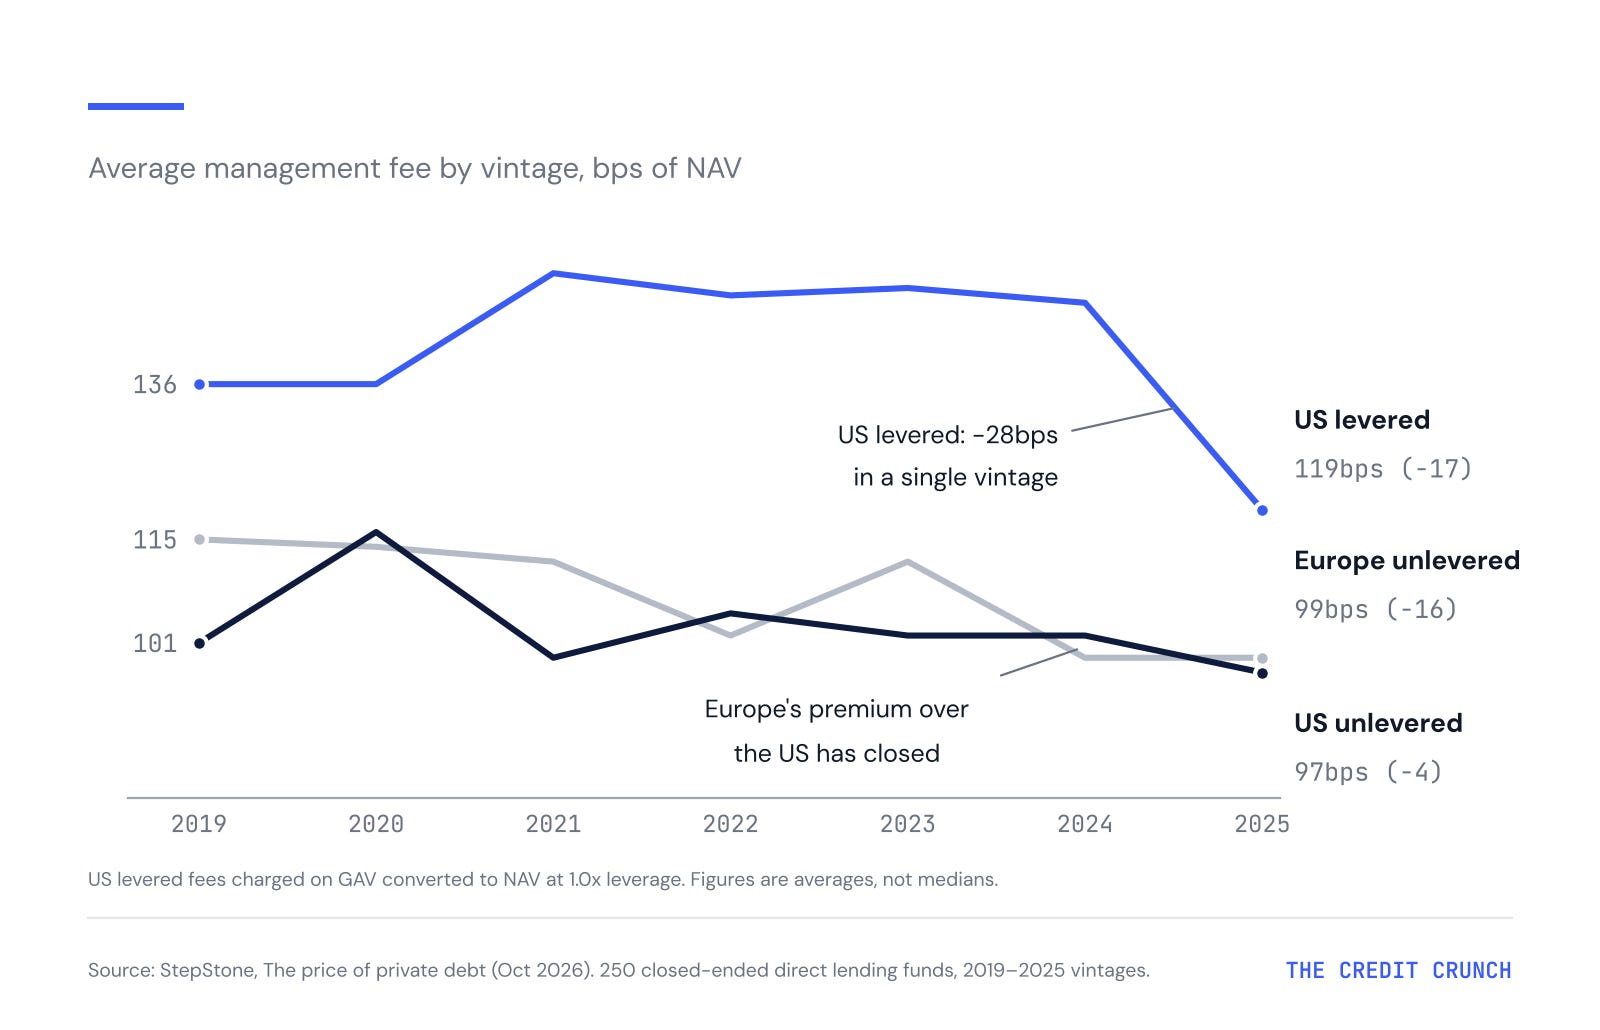
Management Fees: All roads lead to 1%
Europe's premium over the US has gone. European unlevered funds fell from 115bps to 99bps, level with the US at 97bps. US levered funds are still above 1% at 119bps, but cut 28bps in the latest vintage.
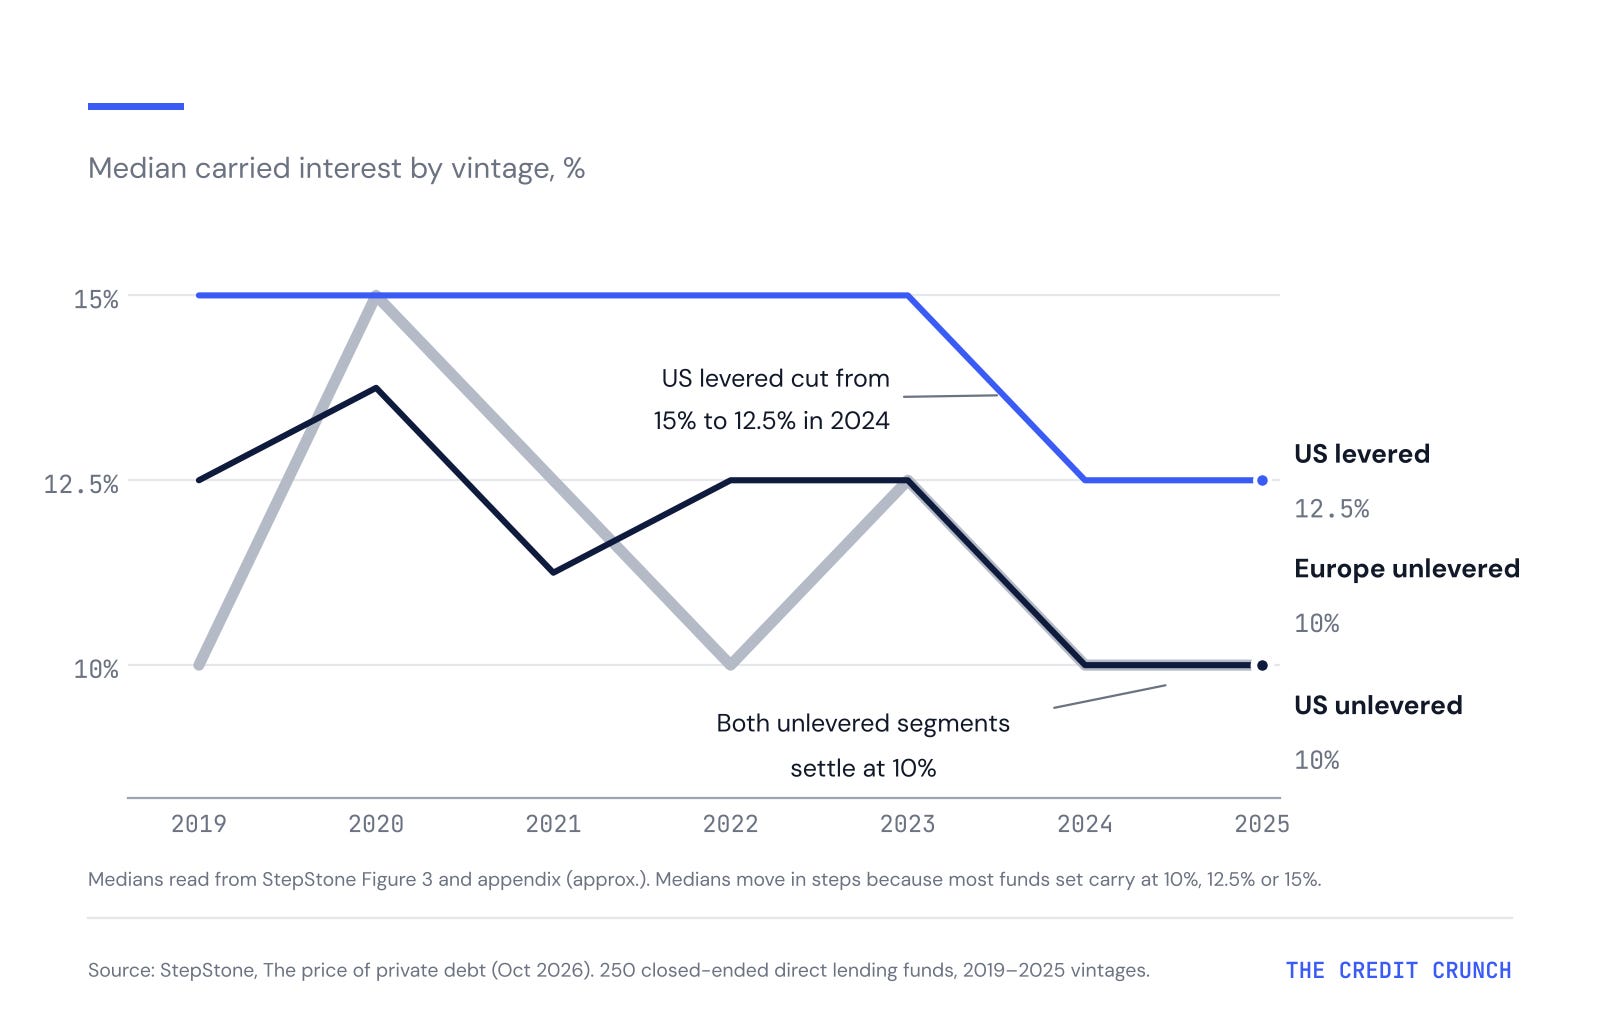
Carry: Settling at 10%
US levered funds cut carry from 15% to 12.5% in 2024. Both unlevered segments have sat at 10% since then.
Hurdles: The quiet win for GPs
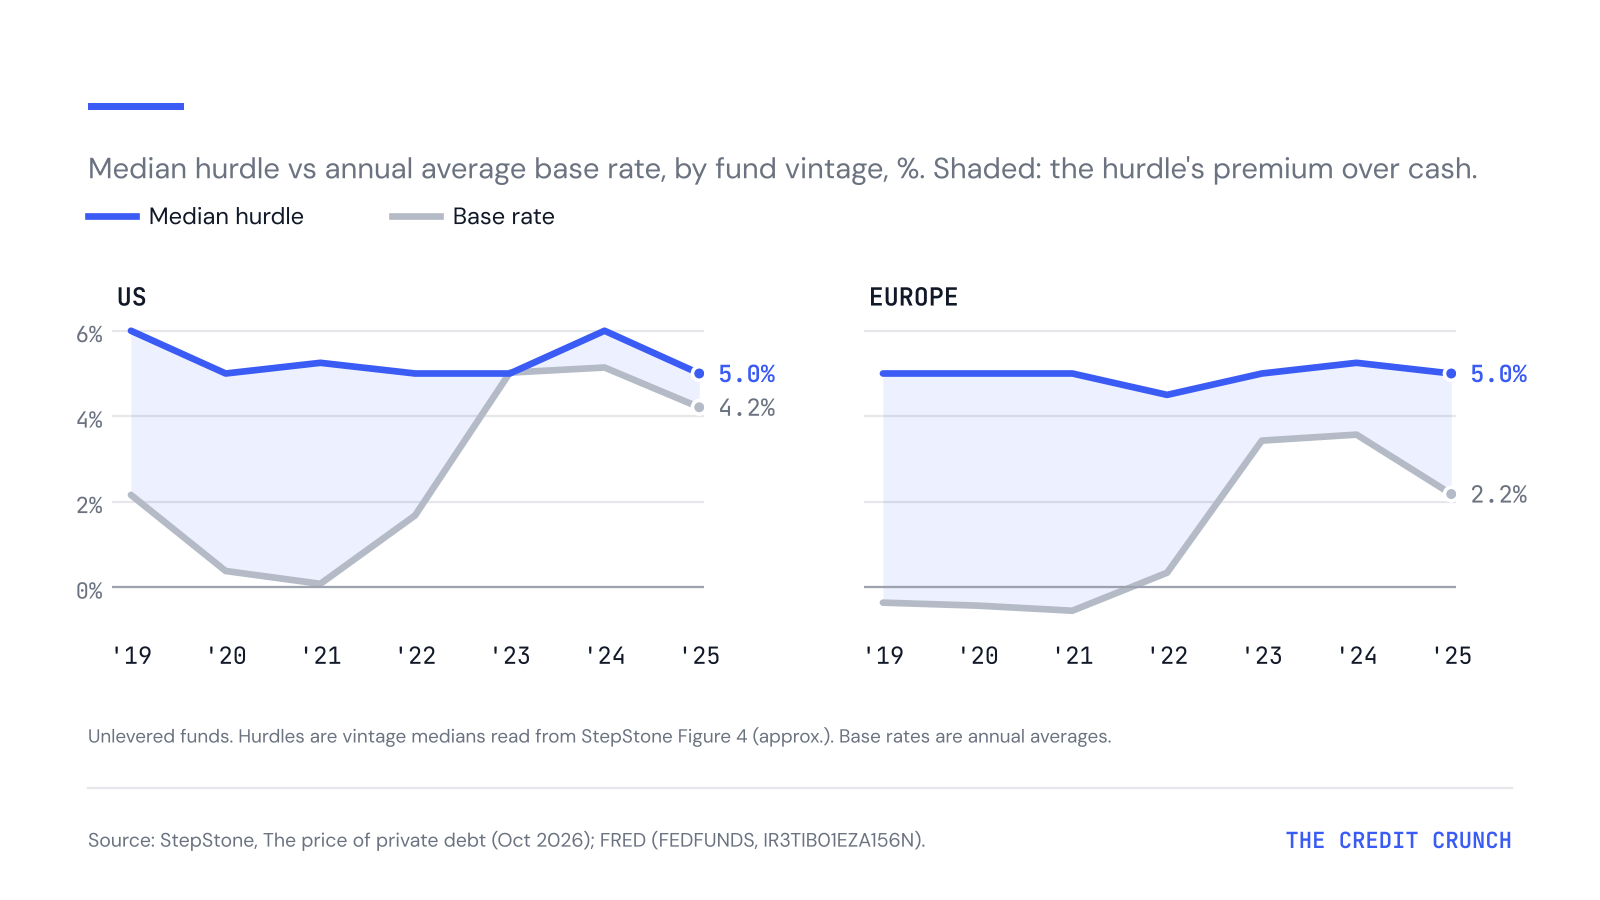
Median hurdles have stayed between 5% and 6% for every vintage since 2019. In the US, a fund now only has to beat cash by under 1 point to start earning carry. In 2021 it needed 5.2 points. Carry is now close to guaranteed for any fund that does better than a money market fund.
The Direct Lending Term Sheet
💰Fundraising News
Direct lending
Ares | $8bn first close across two direct lending funds
Ares raised $8bn across two direct lending funds. Ares Senior Direct Lending Fund IV has secured nearly $6bn in equity and Ares Senior Direct Lending Core, its first open-ended institutional direct lending product, more than $2bn, according to a person familiar with the matter.
PennantPark | $1.2bn Senior Credit Fund II
PennantPark, a Miami-based middle-market lender, closed its $1.2bn Senior Credit Fund II. The fund makes senior loans to sponsor-backed core middle-market companies with $10–50m of earnings.
Continuation vehicles
Tree Line | $680m continuation vehicle
Tree Line Capital Partners, a San Francisco-based direct lender, closed a $680m private credit continuation vehicle holding first-lien loans to more than 60 US lower middle-market companies. PGIM and LGT Capital Partners led the transaction.
The deal follows PGIM’s announcement earlier this year that it was expanding into private credit secondaries, with plans to deploy up to $1bn over two years.
KKR | $460m+ first credit continuation vehicle
KKR closed a $460m private credit continuation vehicle. The vehicle holds the assets of KKR Lending Partners III, a $1.5bn direct lending fund that completed fundraising in 2017. Existing investors could either sell for liquidity or roll into the new vehicle on substantially the same terms. Allianz Global Investors led the transaction.
PennantPark | $745m Credit Secondary Fund
PennantPark closed its $745m Credit Secondary Fund continuation vehicle. It gave limited partners in legacy private funds liquidity while securing additional unfunded commitments to support follow-on financings and new investments.
Specialist strategies
Acore | $1.1bn Opportunistic Credit II (CRE)
Acore Capital, a US commercial real estate manager, closed its $1.1bn Opportunistic Credit II fund. To date, AOC II has committed $400m of capital across 14 deals.
Vistara Growth | Evergreen Structured Opportunities Fund
Vistara Growth, a Vancouver-based venture debt investor, launched its sixth fund as a permanent evergreen vehicle with a long-term goal of $500m. The fund provides debt and equity to mid- and later-stage North American technology companies and is targeting a $200–250m initial close by the end of November.
Maycomb Capital | $100m Community Outcomes Fund II
Maycomb Capital, a US impact lender, held the final close of Community Outcomes Fund II at its $100m target. The fund lends flexibly to nonprofit and for-profit organisations in early childhood, education, workforce development and health equity. Ballmer Group and UnitedHealth Group anchored the fund.
This newsletter is for educational and entertainment purposes only. It should not be taken as investment advice.