
👋 Hey, Nick here. A big welcome to the new subscribers from CalSTRS, Park Square, and Caprock. You’re now one of the 3,414 subscribers, and you’re reading the 184th edition of my private credit newsletter.
Reading on Outlook? The charts won’t render. Read it online
📕 Reads of the Week
If a company still has its 2021 or 2022-era issuance loan outstanding in '28 or '29, it means they can't refinance
Market Updates
HVAC is just one of the specialty trades that keep benefiting from the Data Center Boom. Data center construction spending rose by 46% year-over-year in Q2, as HVAC contractors alone logged more PE deals in the first half of 2026 than in all of 2025 combined. Link
Lincoln’s Q2 2026 European Private Market Index. Link
“In the current environment, it’s difficult to find scenarios where real estate equity would outperform current pricing on real estate debt”. Link
Manager & Deal Updates
🎧 Crossroads with Oaktree’s Bob O’Leary and Armen Panossian. Link
The main constraint on our industry is not fundraising. In a market where deal volumes have contracted, and competition is intensifying, the real challenge is finding enough quality investment opportunities. ICG just raised its $14 billion European Corporate IX. Just before the fundraise was announced, CEO Benoît Durteste sat down to discuss the outlook for private credit. Link
Partnership Updates
Fasanara, a British alt manager, is partnering with stablecoin issuer Tether to launch StableFund, a private credit vehicle that aims to raise as much as $3 billion. Tether has committed $400 million to the fund, which Fasanara Capital will deploy into short-term, asset-backed loans. Tether will also source USDT-linked financing opportunities and provide the infrastructure for moving funds. More here
Secondaries Updates
PennantPark, a US middle market credit manager, closed its $745 million Credit Secondary Fund. The continuation vehicle was led by Pantheon. More here
Bridgepoint Credit, a UK-based credit manager, closed a ~$1.4 billion continuation fund led by Pantheon. The fund acquired ~€1.2bn of commitments from Bridgepoint Direct Lending II, a 2017 vintage direct lending fund, and is weighted towards senior secured credits across healthcare, services and technology sectors, with borrowers across the UK, DACH, Nordics, Benelux and French middle market. More here
BDC Redemptions
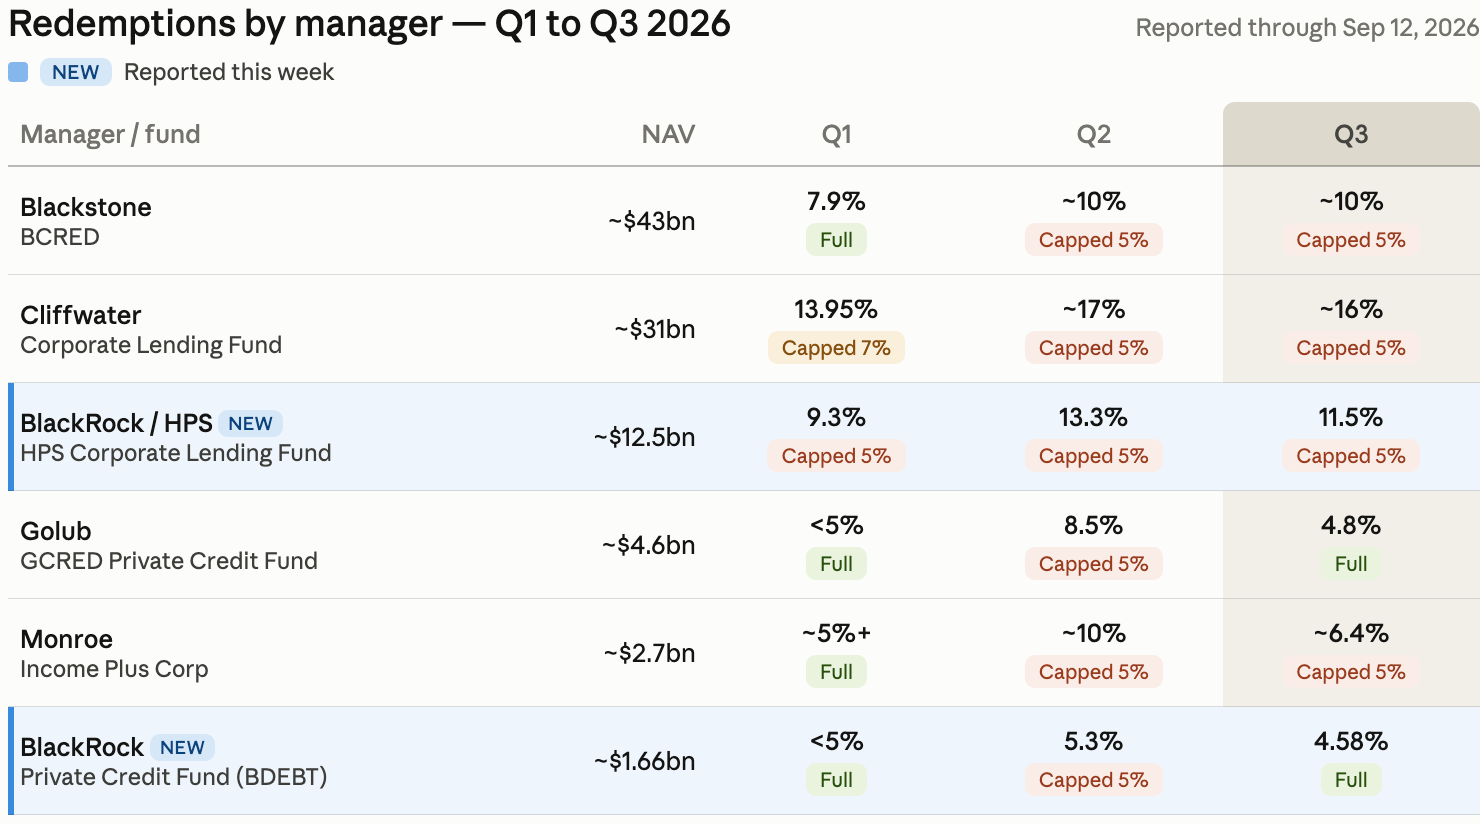
Q3 26 Update: Week 2
Last week saw two more BDC funds announce Q3 redemptions:
Redemption requests have fallen for all managers so far.
BlackRock’s BDEBT received redemption requests lower than its cap
All other managers capped payouts at 5%.
“We’re short everything. We’re short the managers, we’re short the insurers, we’re short the data centers. Not all of them, but the ones that we like the least”
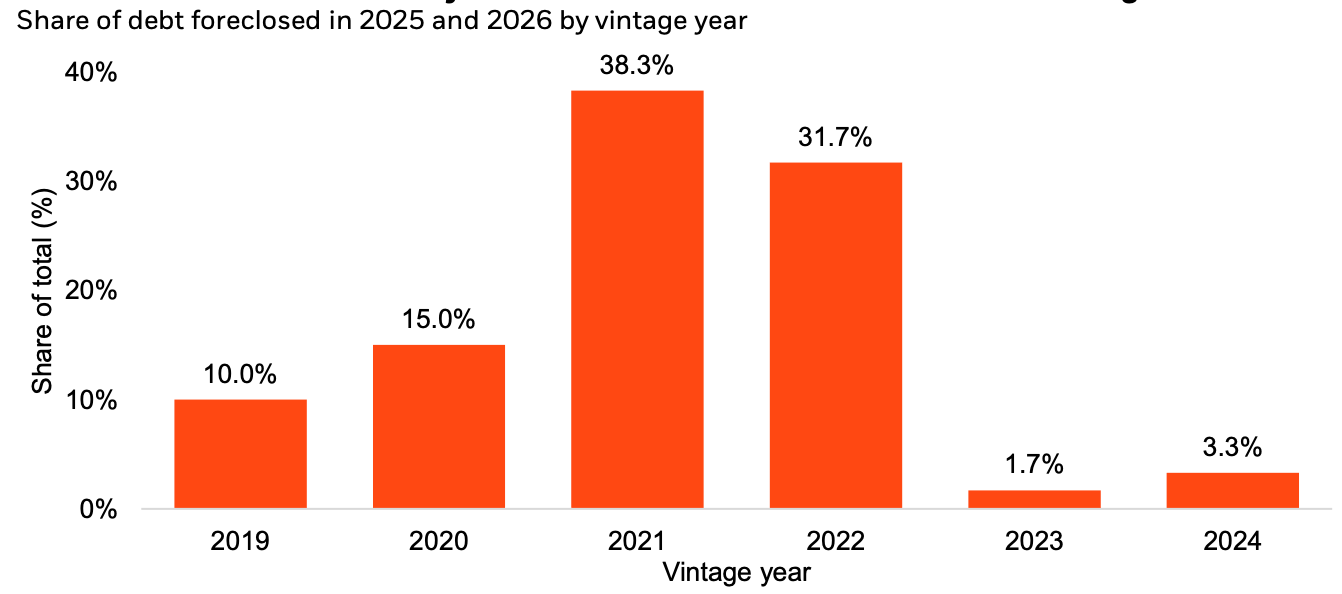
The 2021–22 Vintage Comes Home to Roost
BlackRock published a private credit update. Below are my highlights:
👉Read BlackRock’s private credit update
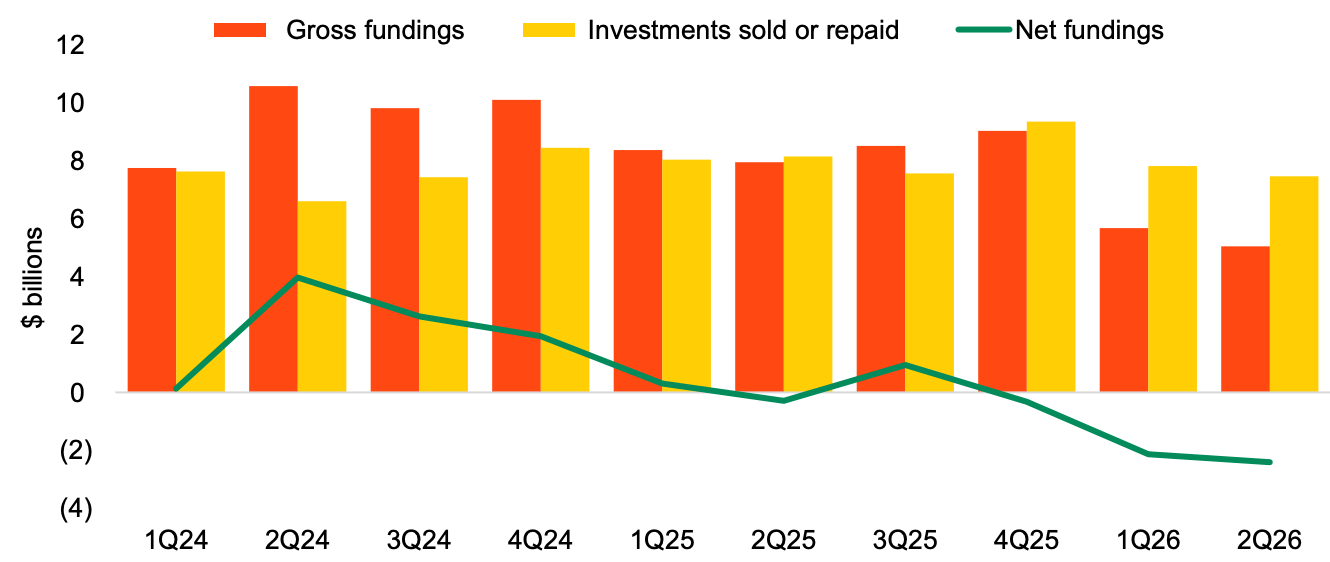
The 12 largest BDC portfolios are shrinking
Investments sold or repaid exceeded fundings for the 3rd quarter in a row
Not only that, but the trend has worsened
This is largely driven by weak deal activity, as investments sold or repaid remain broadly consistent with the long-run average.
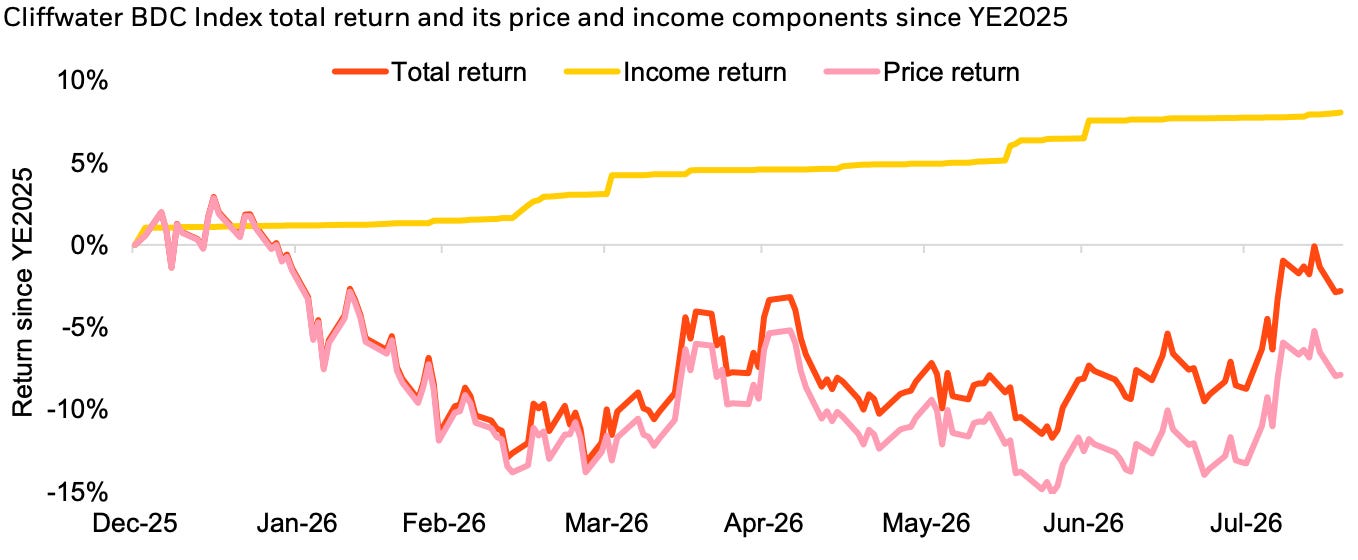
Total YTD BDC Returns are nearly back at 0%
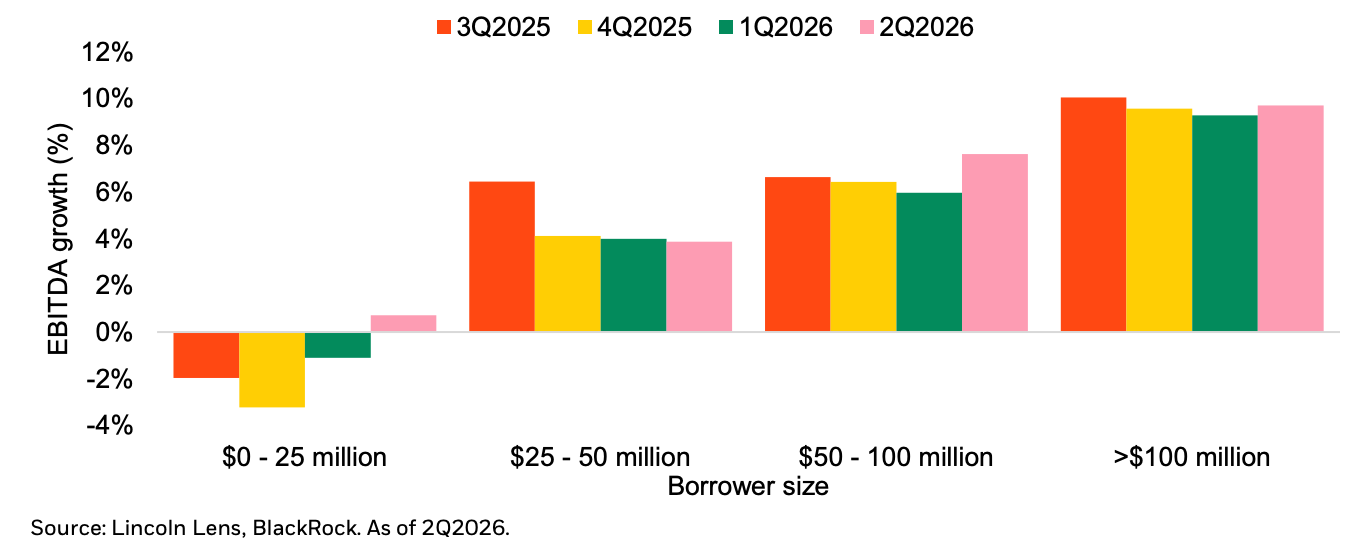
Smaller borrowers continue to grow more slowly
70% of foreclosure activity is concentrated in loans originated in 2021 and 2022
👉Read BlackRock’s private credit update
💰Fundraising News
ICG’s $14 bn European Corporate IX
ICG announced a final close of ~$14 billion for its Europe Fund IX. The flagship European Corporate strategy will target 15-20 investments in Western Europe across middle and upper-middle market companies, with deal sizes ranging from €250 million to €1 billion. The investments are generally industry-agnostic and will include a blend of debt and equity-like investments.
Jefferies’ $4 bn European direct lending strategy
Jefferies Credit Partners has raised $4 billion for its European direct lending strategy. The fund’s perpetual structure provides institutional investors with a portfolio of sponsor-backed, senior secured private credit investments across Europe and the UK. The fund will primarily focus on middle market and upper middle market deals.
HarbourVest’s $2.4 bn Credit Secondaries Strategy
HarbourVest raised $2.4 billion in initial commitments for its new private credit secondary strategy. The capital sits across several vehicles, including a senior credit secondary fund and an opportunistic credit secondary vehicle, and the firm has not disclosed an overall target, with fundraising expected to run through 2027. Around $500 million has been deployed across five transactions, three GP-led and two LP-led, with several hundred million dollars of further opportunities in the pipeline.
Hercules Capital $2.3 bn Venture & Technology Lending
Hercules Capital, a US Venture Lender, raised $2.3 billion across two institutional private credit vehicles. The vehicles are the Hercules Evergreen Fund, a perpetual open-end fund, and Hercules Growth Lending IV, a closed-end fund, both lending to growth-stage technology and life sciences companies.
EIG’s $1.9 bn Infrastructure Debt Fund VI
EIG, a US-based energy and infrastructure specialist, closed its $1.9 billion Senior Infrastructure Debt Fund VI. The fund provides senior secured debt investments across a broad range of sectors, including power generation, renewable energy, energy transition infrastructure and other critical infrastructure, with a primary focus on opportunities in the United States and Europe.
Bridgepoint’s Evergreen Fund
Bridgepoint launched a European evergreen direct lending vehicle aimed at institutional investors. The vehicle will be an extension of the firm’s European direct lending strategy; it is not designed as a semi-liquid offering for individual investors. More here
Secondaries Updates
PennantPark, a US middle market credit manager, closed its $745 million Credit Secondary Fund. The continuation vehicle was led by Pantheon. More here
Bridgepoint Credit, a UK-based credit manager, closed a ~$1.4 billion continuation fund led by Pantheon. The fund acquired ~€1.2bn of commitments from Bridgepoint Direct Lending II, a 2017 vintage direct lending fund, and is weighted towards senior secured credits across healthcare, services and technology sectors, with borrowers across the UK, DACH, Nordics, Benelux and French middle market. More here
This newsletter is for educational and entertainment purposes only. It should not be taken as investment advice.